Two business owners get the same opportunity: a second location, a new product line, or a large contract that requires hiring ahead of the revenue. One says yes on the spot. The other says, “Let me think about it,” and never revisits it.
Who made the right call? It depends on what their financial statements say.
Every growth decision carries financial risk. Avoiding risk entirely keeps a business small. Taking on too much can sink it. The owners who grow steadily know their risk appetite in business, and they back it with real numbers rather than gut feeling.
Here is how to figure out yours.
What Is Risk Appetite?
Risk appetite is the amount and type of financial risk a business is willing to accept in pursuit of its goals. It answers a simple question: how much could we lose, and how much is worth chasing?
It helps to separate three related ideas:
- Risk appetite is how much risk you want to take to reach your goals.
- Risk tolerance is how much variation from your plan you can live with before you need to act.
- Risk capacity is how much risk your business can actually afford based on cash, debt, and profitability.
The problem shows up when appetite and capacity do not match. An ambitious owner with thin cash reserves has a big appetite and a small capacity. A cautious owner sitting on strong margins and low debt may be leaving growth on the table. Neither knows it until they look at the numbers.
Why Guessing Your Risk Appetite Gets Expensive
Most owners set their risk appetite by feel. Revenue was strong last quarter, so expansion seems safe. A slow month hits, so every investment gets frozen.
That approach creates two costly patterns. You take risks at the wrong time, usually when a strong month hides a weakening cash position. Or you miss opportunities because fear fills the gap where data should be.
Your financial statements already hold the answers. The challenge is reading them in a way that tells you how much risk you can carry. If you are not sure how healthy your business really is today, start with this guide on understanding your business’s financial health.
5 Signals That Show How Much Financial Risk You Can Handle
1. Liquidity: Your Current Ratio and Working Capital
Your current ratio shows whether you can cover short-term obligations. To calculate it, divide your total current assets by your total current liabilities.
Working capital tells a related story. It’s the difference between your current assets and current liabilities, showing how much you have available to support day-to-day operations.
A current ratio below 1.0 means short-term debts exceed short-term resources, a warning sign to hold back on new risk. Many businesses consider a ratio between 1.5 and 2.0 comfortable, though the right range varies by industry.
Working capital deserves the same attention, especially when it comes to trends. Compare your working capital during your most and least profitable months to understand how much your business typically needs. The goal is to maintain enough working capital to cover your needs during slower periods, ideally building toward the stronger levels seen in your most profitable months.
Tracking both measures over time gives you a clearer picture of your financial flexibility and whether your business can comfortably take on additional risk.
2. Leverage: How Much Debt You Carry
Your debt-to-equity ratio shows how much of the business is funded by lenders versus owners. Higher leverage magnifies both gains and losses. If your debt load is already rising, adding a new loan for expansion raises your risk faster than it raises your upside.
3. Cash Runway
How many months could you cover operating expenses if revenue slowed? A business with six months of runway can absorb a failed experiment. A business with three weeks cannot. Building a cushion first is often the smartest risk move you can make.
4. Profit Margin Trends
A single good month does not mean your margins can support new commitments. Profit and loss statement analysis across six to twelve periods shows whether gross and net margins are holding, improving, or quietly shrinking. Shrinking margins are a warning sign that your capacity for risk is lower than your revenue suggests.
5. Revenue Concentration
If one or two clients make up a large share of revenue, you are already carrying significant risk. Losing a key account could erase the cushion you were counting on for expansion. Factor that exposure in before adding more.
How to Set Your Risk Appetite in 4 Steps
Step 1: Define what you are chasing and what you cannot lose. Write down the growth goal and the non-negotiables. Payroll, tax obligations, and a minimum cash balance usually top the list.
Step 2: Measure your risk capacity. Use the five signals above. Trend analysis of financial statements matters here because direction is just as important as the current number. A current ratio of 1.6 that is falling looks very different from one that is rising.
Step 3: Write a simple risk appetite statement. Keep it to one or two sentences. For example: “We will invest in growth as long as our current ratio stays above 1.5, we keep three months of operating expenses in reserve, and net margin stays above 8%.” Now every decision has a clear test.
Step 4: Review it monthly. Your capacity changes as your numbers change. A monthly review lets you lean in when conditions are strong and pull back before small problems turn into emergencies. For practical ways to reduce exposure along the way, see these 15 smart financial risk management strategies.
Your Risk Appetite Should Change as Your Business Grows
Risk appetite is not fixed. A newer business often needs to accept more risk to gain traction, but it usually has the least capacity. A growing business can take calculated risks if margins and cash flow support them. A mature business may focus on protecting what it has built, especially if a sale or succession is on the horizon.
Owners running multiple locations or franchise units face an extra layer of complexity. One unit may have room to expand while another needs tighter controls. Comparing units side by side helps you allocate risk where it has the best chance of paying off, which is exactly what our financial analysis for business groups is designed to support.
Whatever your stage, tie your risk appetite to a written plan. If you do not have one yet, this step-by-step guide to creating a financial plan for your small business is a good place to start.
Where Accountants and Advisors Make the Difference
Many business owners have never been shown how to connect their statements to their risk decisions. That is a major opportunity for accountants, bookkeepers, and financial advisors.
When a client asks, “Can we afford to expand?”, the interpretation of financial statements becomes the most valuable service you offer. Walking a client through liquidity, leverage, and margin trends turns a compliance relationship into a strategic one. Firms that want a structured way to deliver that conversation can explore our financial advisory certification program, which trains teams in a proven analysis framework.
Learn It Live: Seminars With Ruth King
Reading about risk appetite is a good start. Seeing it worked through with real financial statements is where it really clicks.
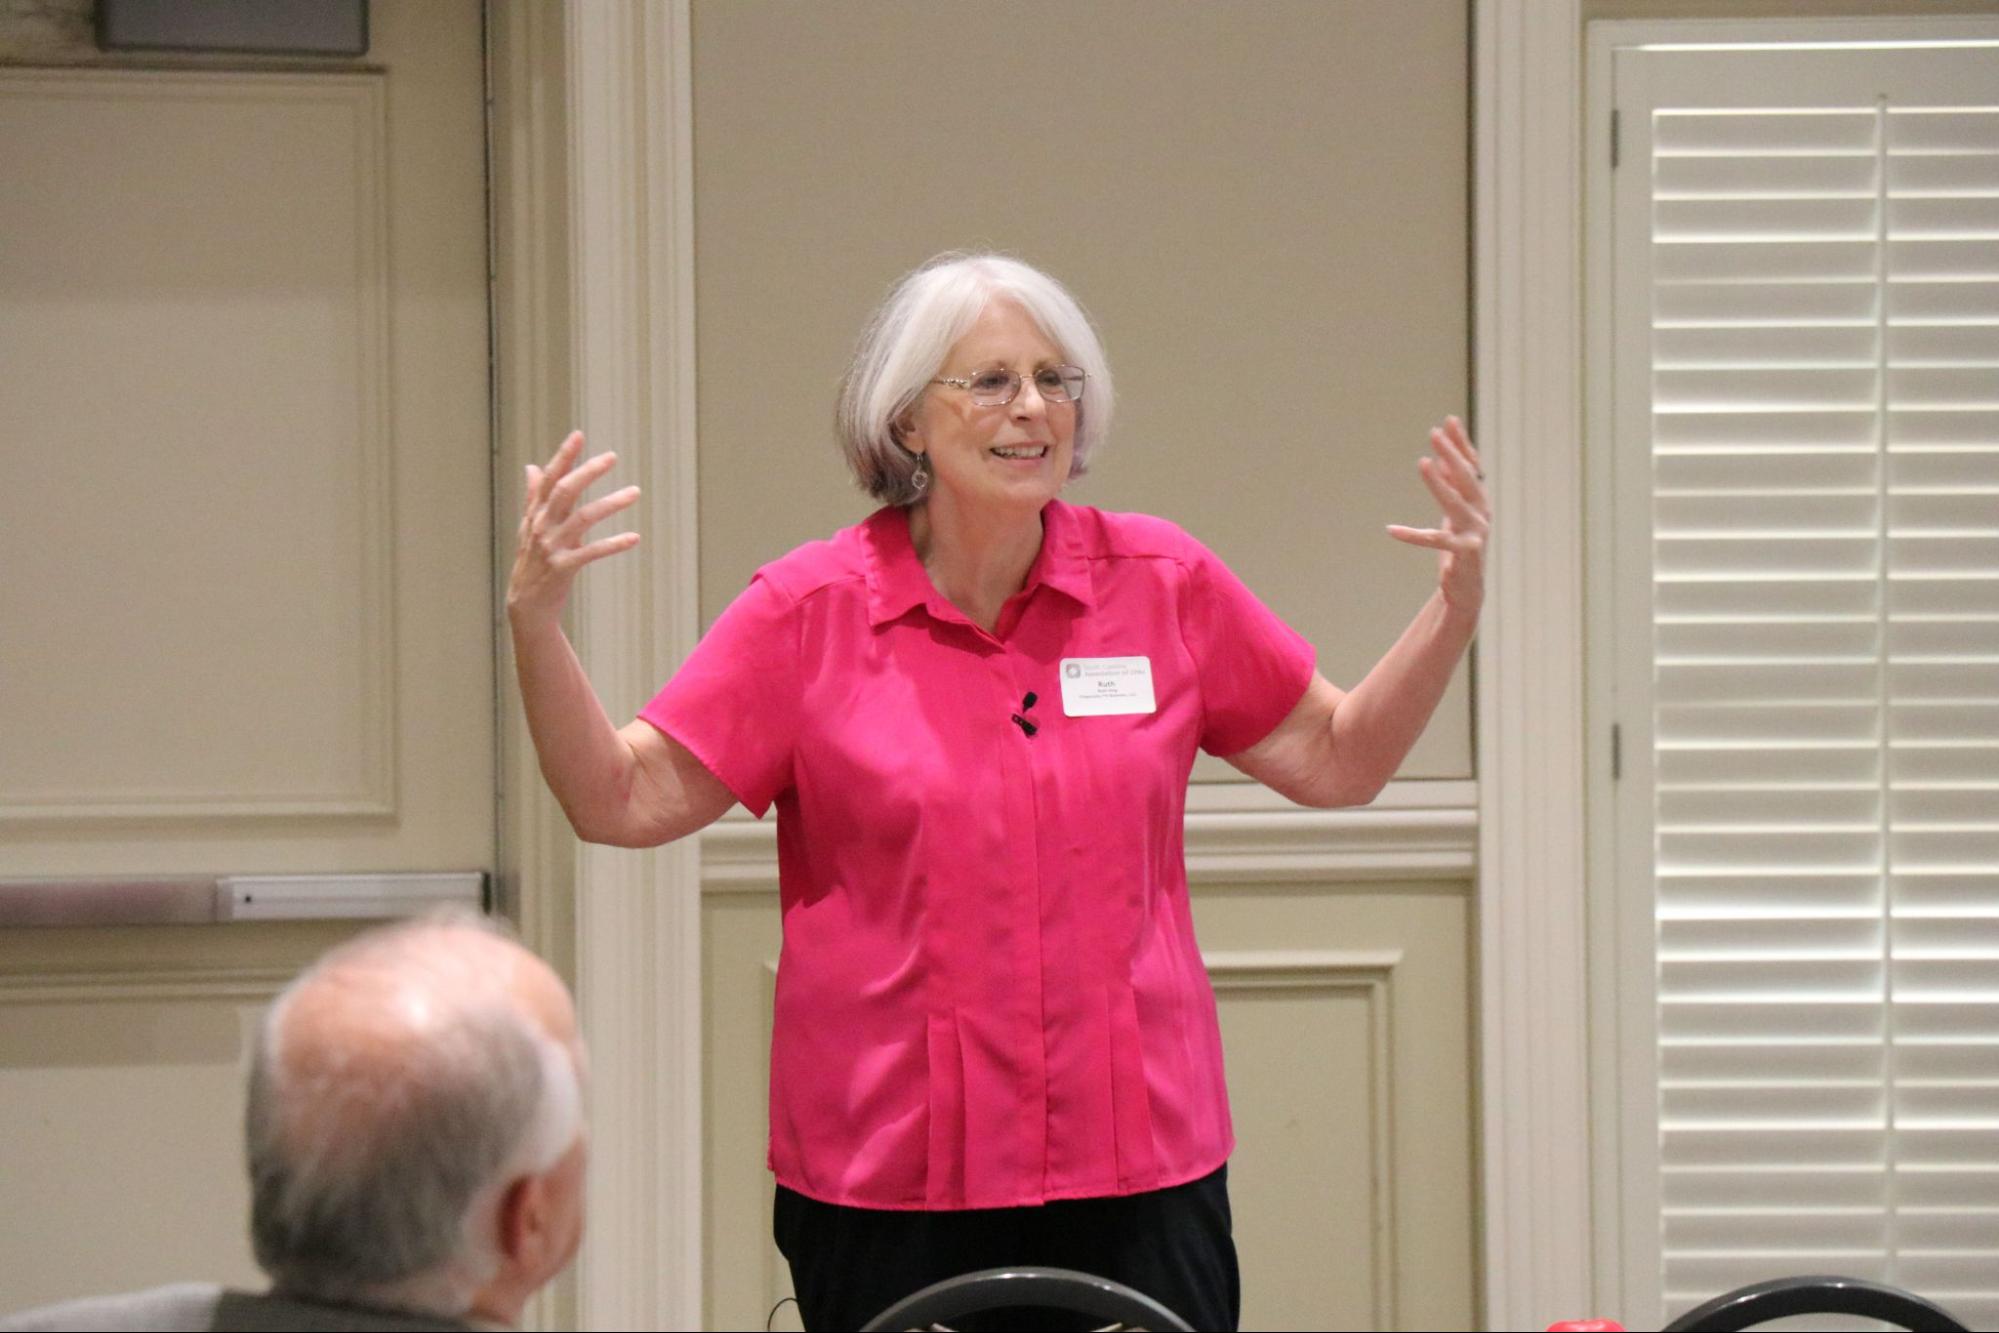
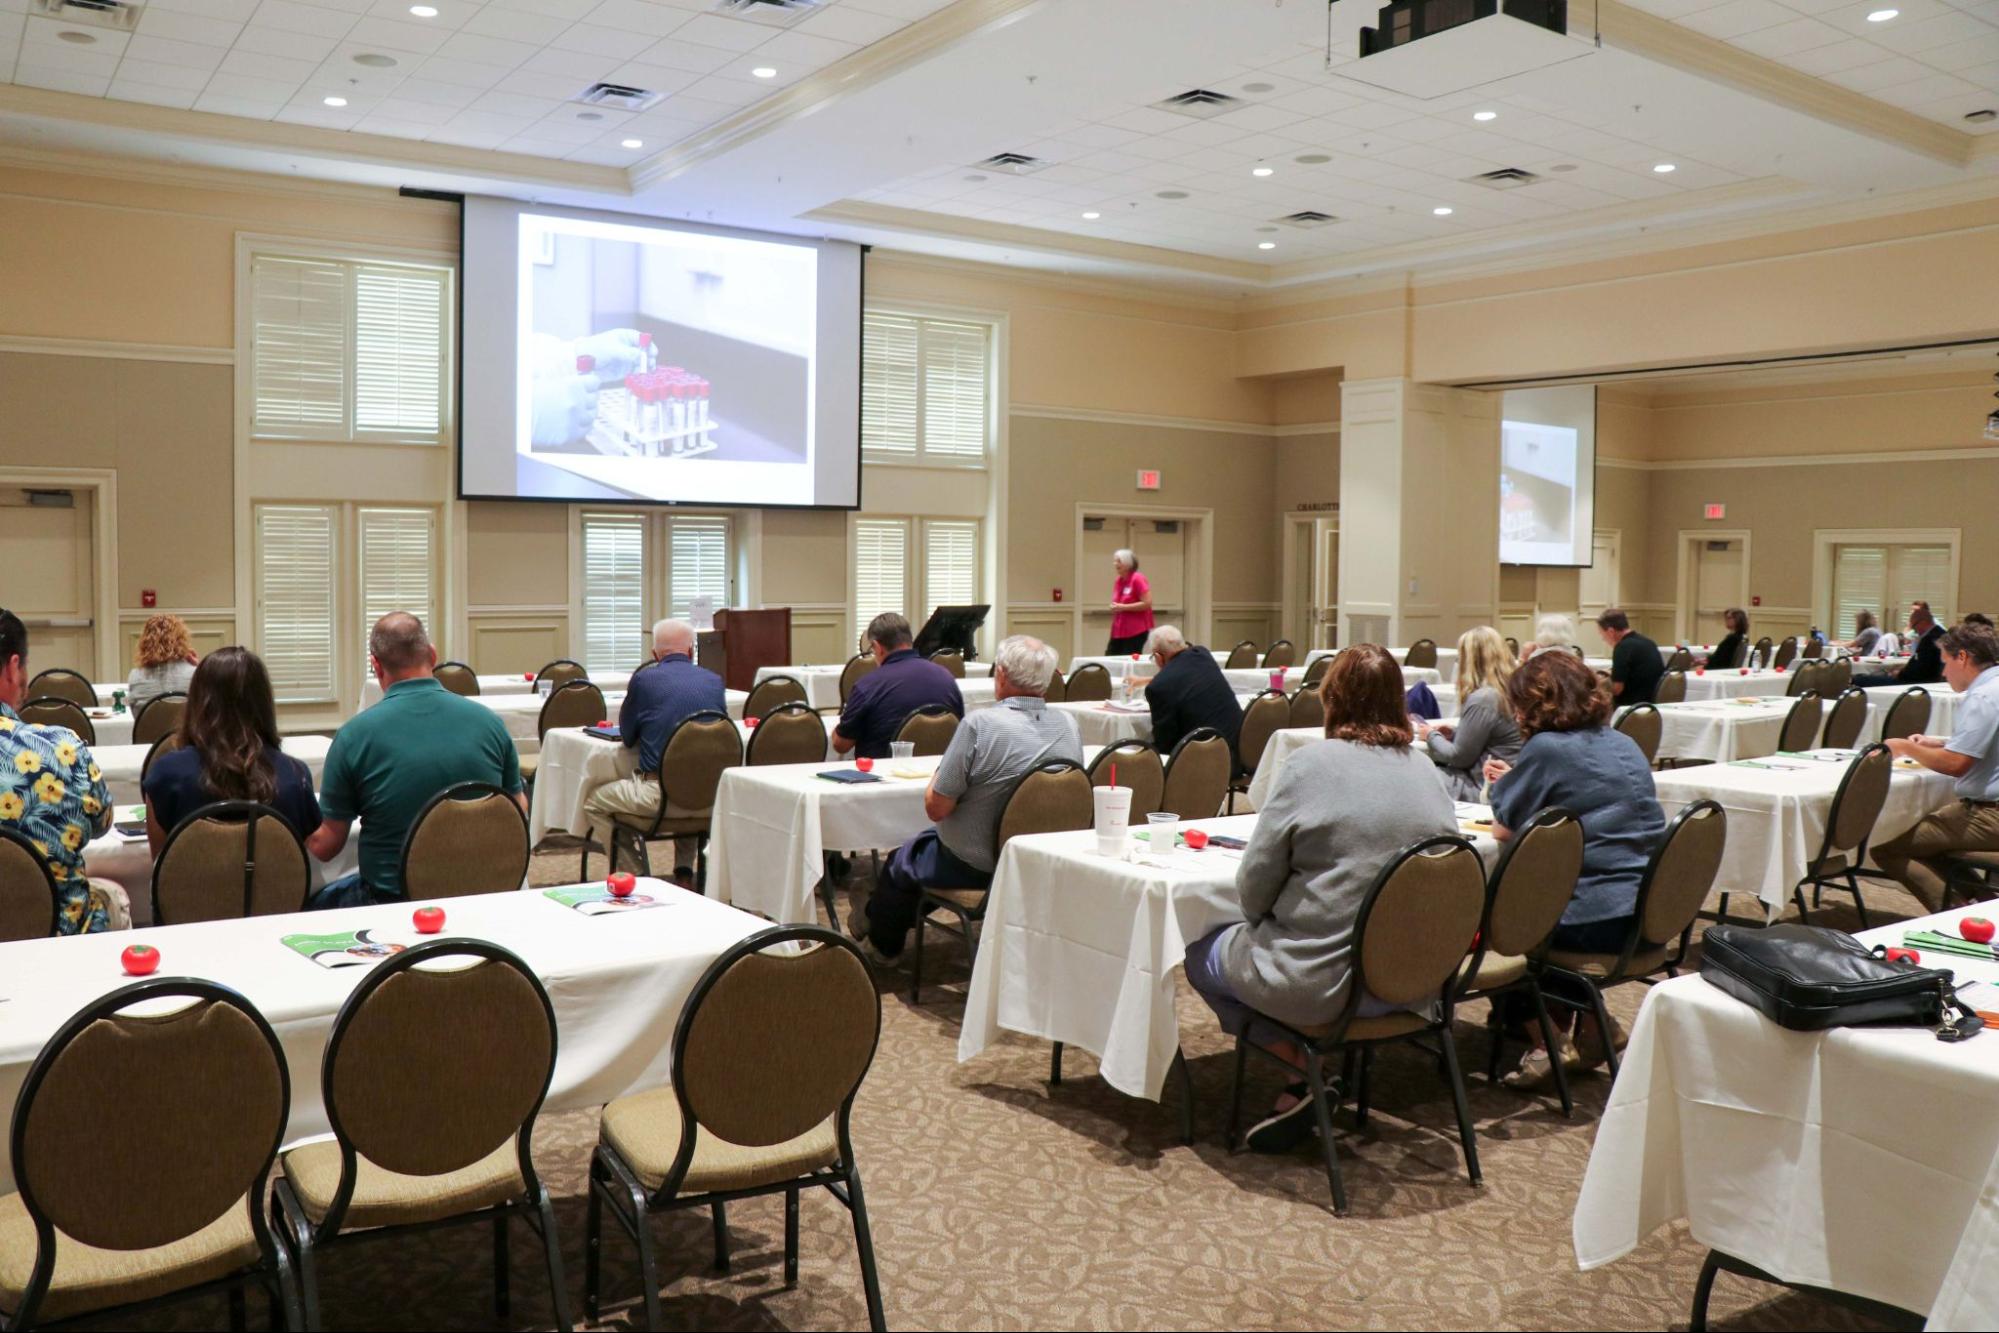
Ruth King, founder and CEO of Financially Fit Business, LLC, has spent decades teaching business owners and accountants how to read the story behind their numbers. She has been helping businesses become and remain profitable since 1981, and she created and leads Understanding Financial Analysis Trends, a group live course sponsored by the National Association of State Boards of Accountancy (NASBA). Her speaking schedule has taken her to state and national CPA association meetings, trade shows, manufacturers, and distributors in 49 of the 50 states, including the South Carolina Association of CPAs.
Ruth’s sessions are known for being practical and energetic. Rather than lecturing on theory, she walks attendees through the graphs and trends that reveal whether a business is heading in the right direction. In her CPE courses, accountants learn how to present profit and loss trend graphs to clients and how to recommend next steps when a business is not trending well financially. That is exactly the skill set behind setting a smart risk appetite: knowing when the numbers support a bold move and when they say wait.
Who attends:
- Accountants, bookkeepers, and financial advisors who want to move beyond compliance work and lead confident advisory conversations, often while earning CPE credit.
- Business owners who are tired of financial statements sitting unopened and want to make growth decisions with clarity.
Ruth holds an MBA in Finance from Georgia State University and is the author of The Courage to be Profitable along with five other award-winning books. If you want to sharpen how you or your team interpret financial statements, an upcoming session is one of the fastest ways to get there. Connect with the Financially Fit Business team to ask about upcoming seminars, or listen to the Financially Fit Business Podcast for a taste of Ruth’s approach.
Turn Financial Risk Into a Clear Decision
Knowing your risk appetite only works if you can see your numbers clearly and often. That is where the right financial management tools for small business come in.
Financially Fit Business is not a bookkeeping tool. It works alongside the accounting software you already use. You upload your Profit and Loss Statement and Balance Sheet, and the platform generates visual dashboards, ratio tracking, cash flow trends, and multi-period comparisons in under two minutes. Its AI flags anomalies and areas of concern, so you can spot a falling current ratio or shrinking margin before you commit to a risky move.
Instead of guessing whether now is the right time to grow, you will know.
Ready to Take Smarter Risks?
For business owners: Stop making growth decisions on gut feeling. See your liquidity, margins, and cash flow trends in one clear view with our financial tracking software for business owners. Book a demo and find out how much risk your business can really handle.
For accountants, bookkeepers, and financial advisors: Help clients answer “Can we afford this?” with confidence. Deliver visual, advisor-ready risk insights through our platform for financial professionals, or review pricing to get started.
Frequently Asked Questions
What is the difference between risk appetite and risk tolerance?
Risk appetite is the overall amount of financial risk a business is willing to take to reach its goals. Risk tolerance is the acceptable range of variation from the plan before action is needed. For example, your appetite might allow investing in a new location, while your tolerance sets the point where you pause if cash reserves drop below three months of expenses.
How do I know how much financial risk my business can afford?
Review your current ratio, debt-to-equity ratio, cash runway, profit margin trends, and revenue concentration. Look at these over several months rather than a single period, since trends reveal whether your capacity for risk is growing or shrinking. Financial analysis software can calculate and visualize these metrics automatically from your existing statements.
How often should a small business review its risk appetite?
Review it monthly alongside your financial statements, and revisit it before any major decision such as hiring, taking on debt, or expanding. A formal reset once a year, or whenever your business enters a new stage, keeps your risk appetite aligned with your actual financial position.